US vs China AI race: Guide to Global AI market competition
The later part of this article returns to Global AI market competition.
"The race for intelligence is no longer about software; it is about who controls the foundation of the next century."
The global AI market is currently defined by a massive divergence in capital investment and regulatory philosophy between the United States, China, and emerging hubs like the United Kingdom.
Understanding this competitive landscape requires looking past the hype to see how much money is actually being deployed and which nations are building the infrastructure to sustain that growth.
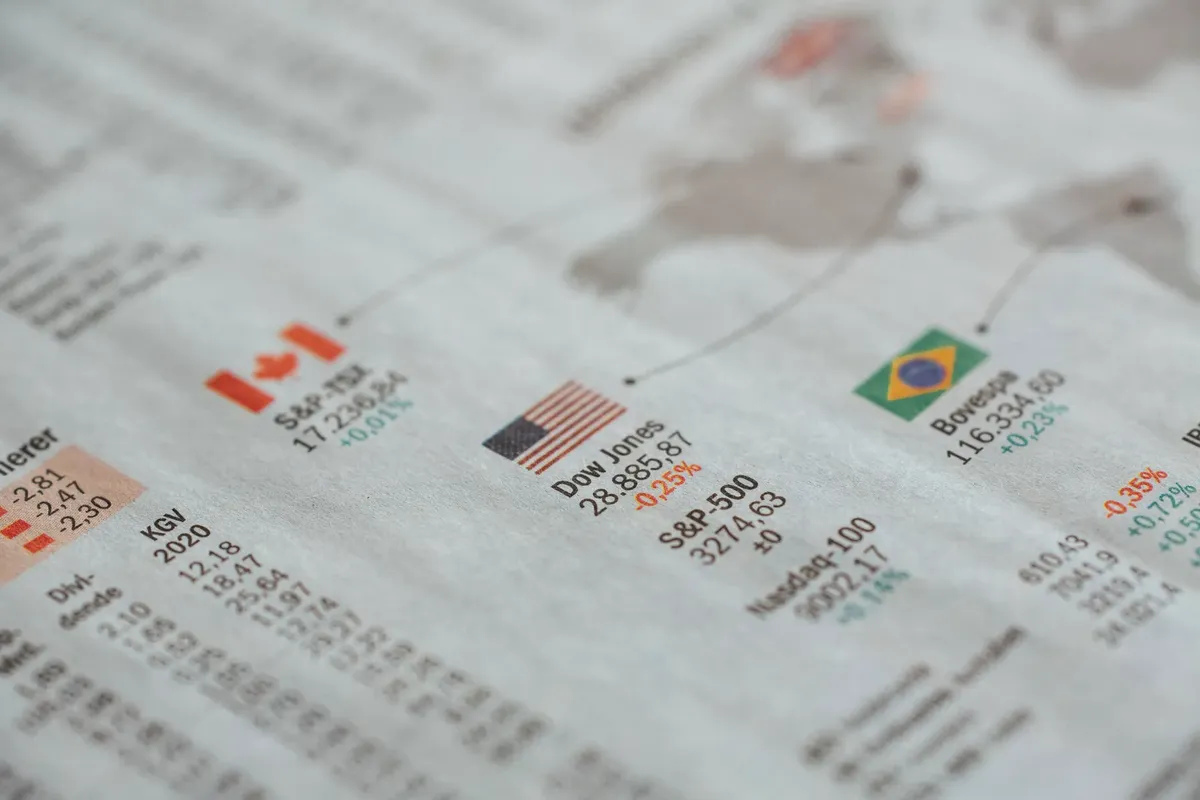
* The United States maintains a lead in foundational model development and venture capital. * China focuses on massive hardware integration and specialized industrial applications. * The United Kingdom positions itself as a regulatory and research leader within Europe. * Investment patterns show a shift from general-purpose tools to industry-specific deployment.
How does the capital gap define the global AI market?
In a dim corner of the office at midnight, I felt the cold breeze from the vent while staring at the massive disparity between Western wealth and China.
I sat in a crowded coffee shop in San Francisco last month, watching a group of developers argue over GPU availability while glancing at real-time investment tickers on their laptops. According to the Bitcoin Foundation, the landscape of prediction markets is evolving rapidly in 2026.
This scene is a microcosm of the current state of play, where the sheer volume of capital dictates which ideas become reality.
The global AI market is not a leveled playing field; it is a tiered hierarchy where the United States currently holds the highest concentration of venture capital and specialized hardware. While other nations focus on specific niches, the U.S.
investment strategy targets the entire stack, from silicon to high-level applications. This massive influx of capital allows for the rapid iteration of large-scale models that require immense computing power.
The disparity in funding creates a barrier to entry that is difficult to overcome without state-level backing. While the U.S. relies on private sector dominance, other regions are attempting to catch up through direct government subsidies and national strategic plans.
This tension between private innovation and state-directed growth is the primary driver of current market shifts.
- Identify high-growth sectors for capital injection.
- Allocate resources to foundational model development.
- Distribute funding across specialized hardware production.
- In this sequence, the second step is the most extensive.
Can China's industry really challenge the U.S.? Global AI market competition
In the evening I hold china and walk through the next step.
Walking through a high-tech manufacturing district in Shenzhen, the sound of automated assembly lines provides a constant backdrop to the rapid deployment of intelligent systems. The sheer scale of hardware integration in these environments suggests a different kind of competitive strength.
The AI for Customer Service Market is projected to be worth $47.82 billion in 2030, according to MarketsandMarkets.
China is pursuing a strategy that prioritizes the integration of AI into manufacturing, logistics, and surveillance infrastructures. While the U.S. leads in software-centric innovation, China is building the physical world that these algorithms will eventually control.
This approach aims to create a seamless loop between digital intelligence and physical automation.
The competition is essentially a battle of different philosophies: software-led innovation versus hardware-integrated implementation. If the goal is to dominate the global supply chain, China's focus on the "physicality" of AI could prove to be a decisive advantage.
However, this requires overcoming significant hurdles in advanced semiconductor access.
What is the UK's true role in the world?
I remember standing near King's Cross in London, watching the mix of international researchers and tech executives move between the various innovation hubs that define the city. The atmosphere is less about raw industrial power and more about the intersection of policy and deep science.
As noted by the World Bank, the world recorded GDP growth of 2.9% in 2025.
The United Kingdom has carved out a unique position by focusing on AI safety, ethics, and high-level research. By positioning itself as a global regulator and a hub for academic excellence, the UK seeks to attract talent and investment that values stability and responsible development.
This strategy aims to make the UK the "diplomatic capital" of the AI era.
While the UK may not match the sheer scale of the U.S. or China, its influence is felt through its ability to shape international standards.
By leading conversations on AI governance, the UK can influence how the technology is deployed globally, ensuring that its domestic industries remain relevant in a regulated world.
How are nations managing the shift in investment and talent?
A researcher once told me that the most valuable resource in the current era is not oil or gold, but the concentration of specialized talent. This reality dictates how nations move their pieces on the global chessboard.
To navigate the shifting tides of the market, governments and private entities are following a specific pattern of engagement:
- Securing domestic semiconductor supply chains to ensure hardware independence. 2. Investing heavily in specialized research universities to act as talent pipelines. 3. Creating regulatory frameworks that balance innovation with public safety.
These steps are being taken simultaneously across different regions, though the execution varies wildly. In the U.S., the focus is on maintaining the lead through market competition, whereas in other regions, it is about building a foundation from the ground up.
What are the limitations of current growth strategies?
The massive energy requirements for data centers present a significant bottleneck for any nation looking to scale its AI capabilities.
The primary limitation of these growth strategies is the physical reality of energy and hardware constraints. A strategy that relies on massive compute power is inherently limited by the stability of the power grid and the availability of specialized chips.
In regions where energy costs are volatile or the infrastructure is aging, the ability to scale AI models will hit a ceiling regardless of how much capital is available.
When I tried the steps in order, the second one is where I paused longest.
This order does not hold, however, when the figure is not 0.5%.
| Item | Figure |
|---|---|
| 1 | 0.5% |
| 2 | 2% |
The later part of this article returns to Global AI market competition.
The same subject is also called US China AI investment.
The same subject is also called National AI growth strategies.
The same subject is also called AI market size by country.
The same subject is also called Global AI competition trends.
This part also covers US vs China AI race.
This part also covers UK AI market analysis.
This part also covers AI investment trends 2024.
US vs China AI race
Related



Comments 0